Auxtail · Case study
Thanks for Visiting
Reach out
Context
Short version · ~13 min read
A patent, a founder, and no idea yet whether anyone would buy it.
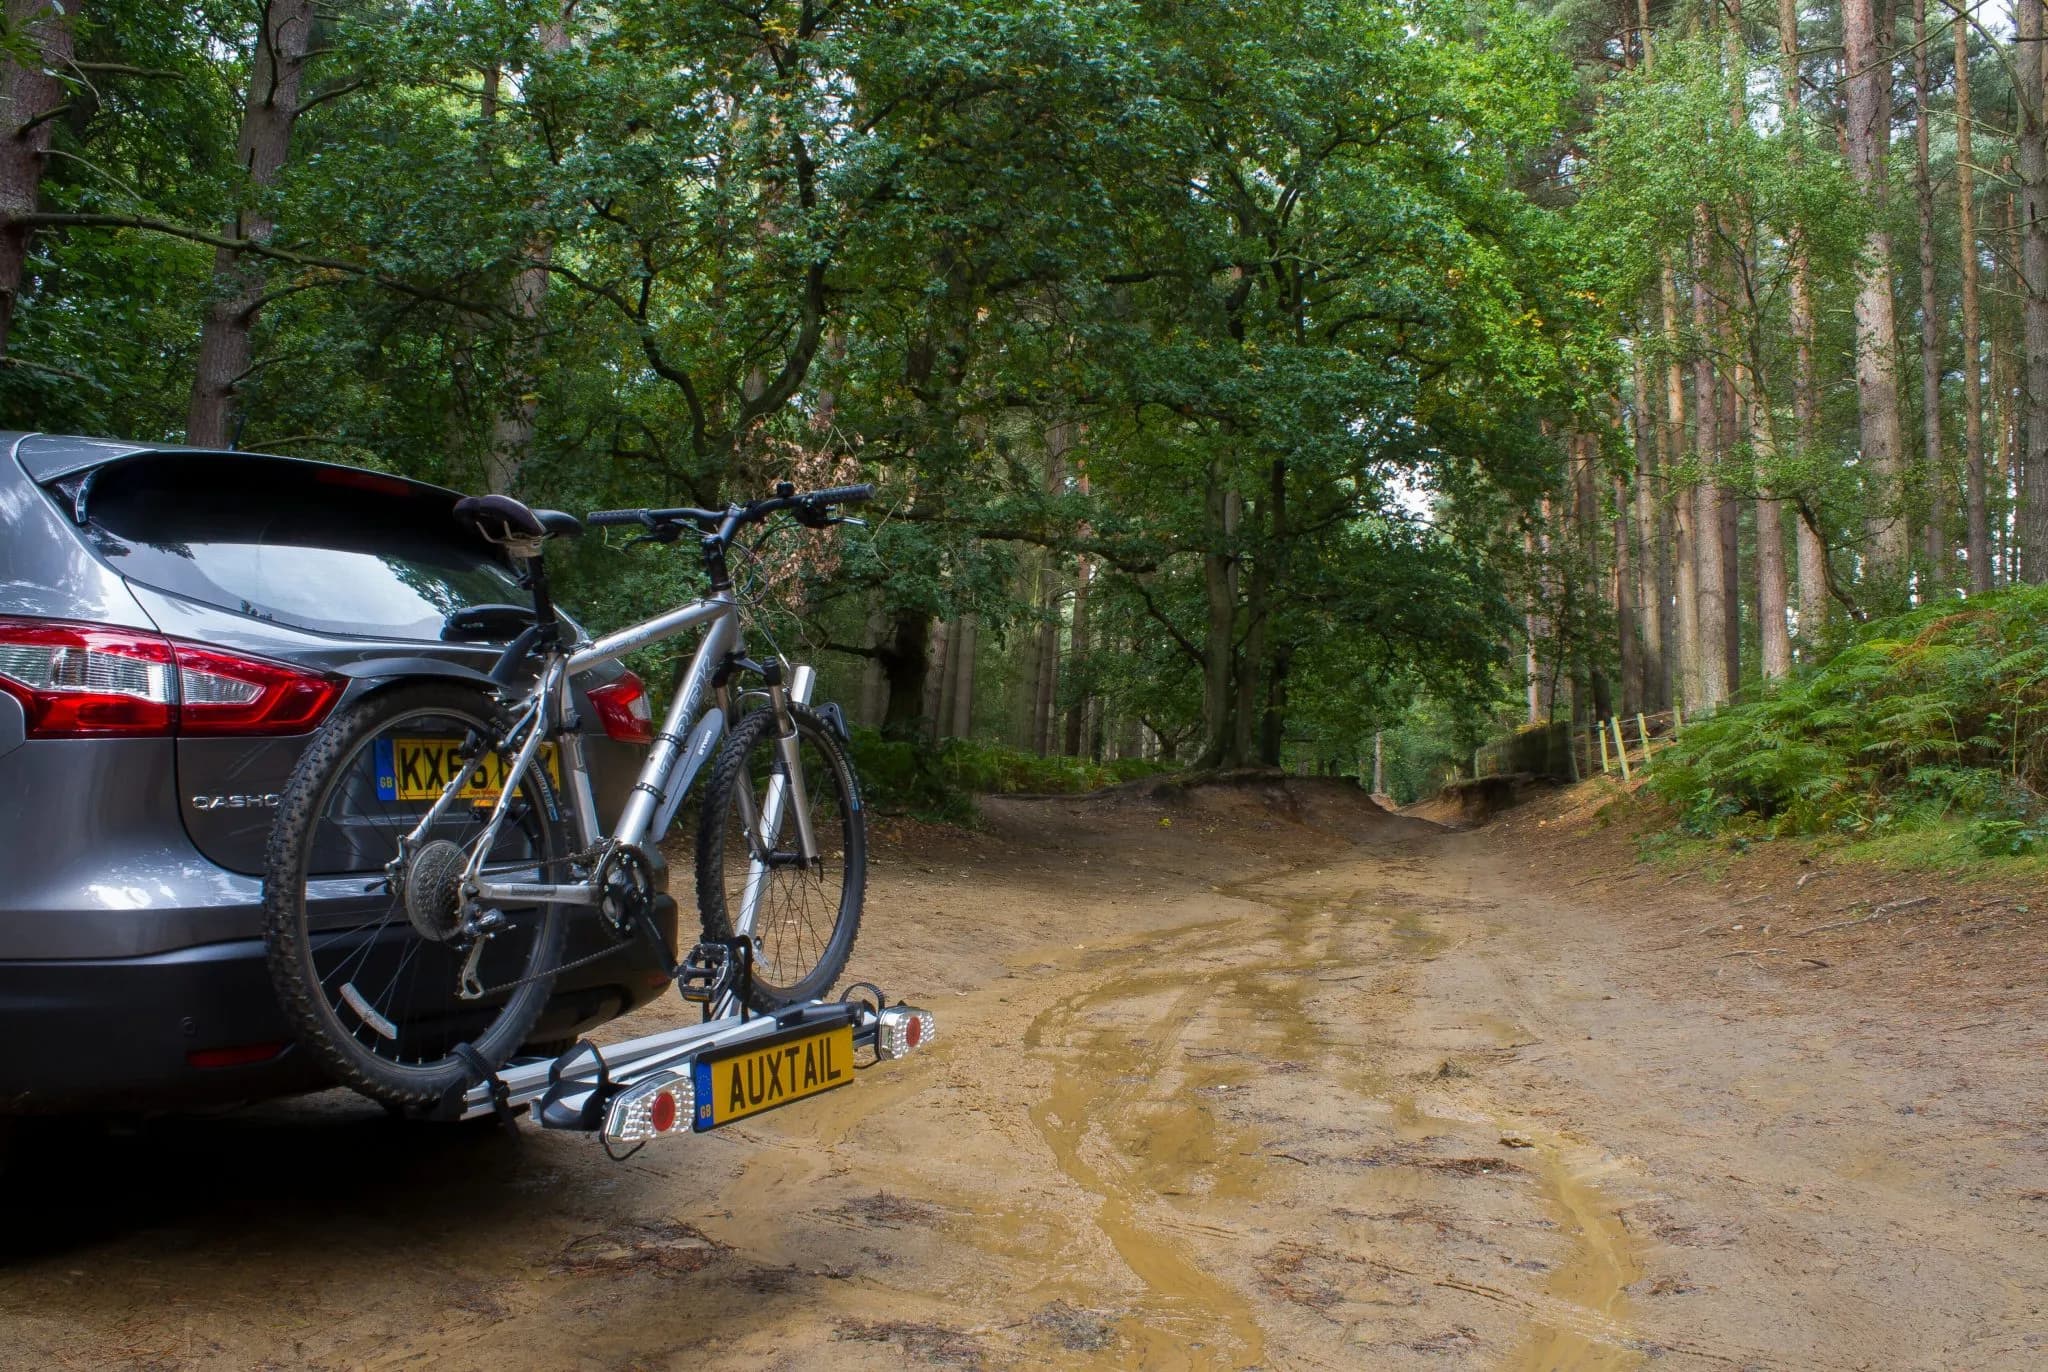
The problem was never the engineering. Craig Broadbent spent 20 years designing towbars at Nissan and the patent was granted. Nobody had asked whether anyone would pay for it, at what price, or through whom.
My solution was to stop selling a rack and sell a system, priced off the value delta rather than the shelf, over 4 decisions that each name what being right costs. The output is a phased commercialisation strategy and the investor deck that carries it, from an MSc dissertation with Auxtail as the industrial partner. The outcome is not in yet: this is a plan, not a product in driveways.
- £44M
- UK market for EV owners who cycle and carry bikes, sized bottom up
- 23
- People heard from directly: 20 survey responses and 3 expert interviews
- 4 of 4
- Validation thresholds met, all 4 written down before the survey went out
- 15%
- Lift in adoption intent once the range case was put to the same people
- £1,495
- Launch price, argued from the value delta rather than from the shelf
- 18 months
- From first units in driveways to the OEM conversation, in 3 gated phases
The process, in 19 steps
Open the at the top of the screen to jump between steps at any time.
The rack industry is still designing for petrol
01Market dynamics
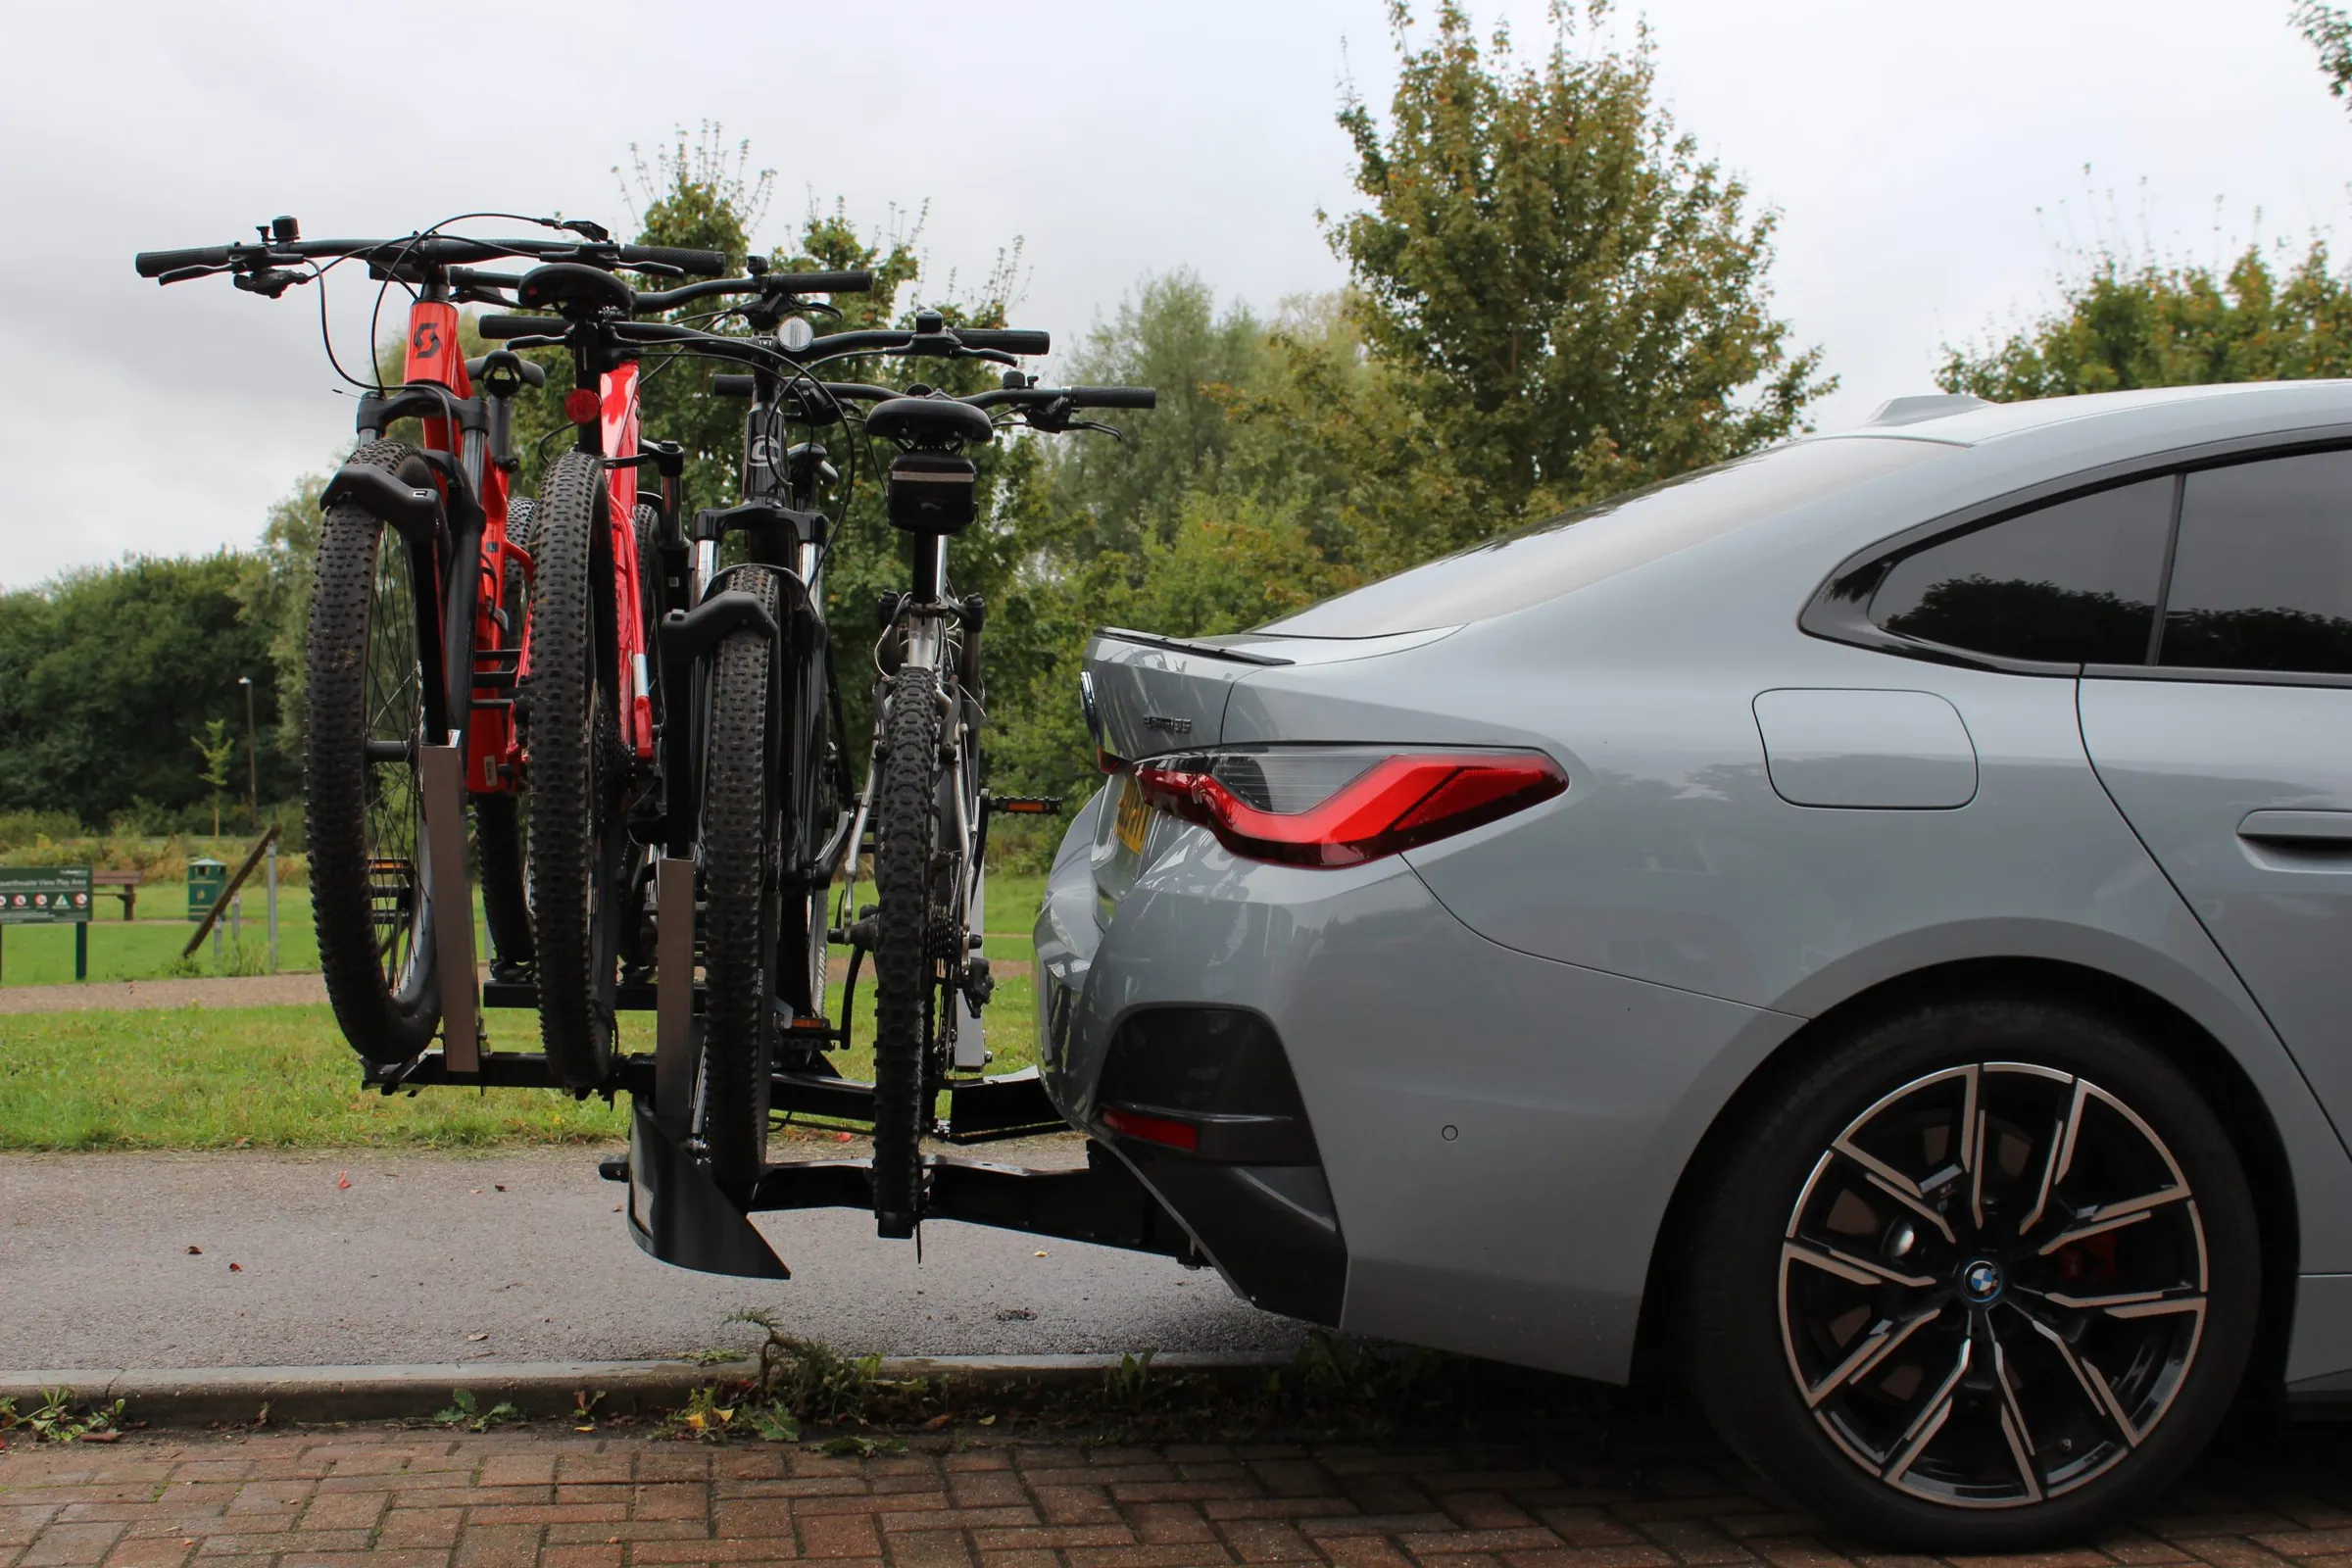
Every UK rack was designed around a petrol car. An EV changes 3 things at once: drag costs range, the towbar is capped, and buyers care how it looks.
- Roof racks
- +26%
- Rear racks
- ~5%
- Towbar ceiling
- 70kg
- What is left
- 2 e-bikes
Aerodynamic drag added by a roof-mounted carrier, and an EV pays for drag in range
Efficiency lost to a conventional towbar rack, before you have loaded anything
European limit on a rear-mounted system, with a 300mm cap on how far it may extend
A rack weighs 17kg to 20kg of that ceiling, and an e-bike is around 25kg
- PPolitical
- £2 billion went into cycling and walking from 2020 to 2025, and the Cycle to Work scheme covers racks.
- So: A tax advantaged way in
- EEconomic
- The rack market grows about 5% to 7% a year, while rising living costs squeeze what people spend.
- So: Price on value, for buyers who can pay
- SSocial
- Over half the UK lives within a mile of a cycle route, and 88,000 bikes were stolen in England and Wales in 2019/20.
- So: Security sells
- TTechnological
- Premium racks are adding automated locks and connected features, and Thule bought Quad Lock to move that way.
- So: Room for app connected locks later
- EEnvironmental
- Net Zero names active travel, and an aerodynamic accessory can add 2% to 3% to an EV's range.
- So: Prove the aero, then market it
- LLegal
- A rear rack must keep the plate and lights visible or the insurance is void, and UKCA has replaced CE.
- So: Compliance becomes a selling point
Perceived use value
Perceived value
Sells at
£1,495 to £1,795
Where it has to land
Rear wake integration, install once, compliance pack, up to 4 bikes
What it still has to prove
Unproven. No units in customers' hands, and OEM approval is years of testing away
TAM 1.1M BEVs, 23.67% own bikes, 20% carry them by car, at £850. Ring areas are drawn in proportion to the figures.
Bottom up from 1.1 million UK battery EVs, the 23.67% of them who own bikes, the 20% who carry bikes by car, at an £850 average selling price. Cross checked top down against UK and European rack industry reports.
- LargeLaunch target
Active families with an EV
Families in urban or suburban areas who regularly commute hybrid.
- Reduced range
- Loading and unloading
- Design conscious
- Parking and manoeuvring
- Theft
- Medium
Outdoor leisure travellers
Cyclists who combine EV travel with weekend or holiday riding.
- Long distances
- Reduced range
- Weather
- Several bikes at once
- MediumLaunch target
Club and group riders
Adults who ride at events and group rides, and drive there in an EV.
- Several bikes at once
- Reduced range
- Small
Professional cyclists and triathletes
Athletes whose specialised bikes need care on the way to an event.
- High value bikes in weather and over distance
- Theft
The 2 launch targets are the early adopters the SOM counts, and the people the survey went to.
The Five Forces said it from the other end: rivalry is high, substitutes are everywhere, and still nobody solves drag, install effort and EV looks together. Not a missing category. A missing answer inside a crowded one.
Then I went and asked
02Primary research
Desk research proves a gap exists, not that anyone minds. So the second half ran as a Lean Startup loop: 4 thresholds set in advance, 20 EV owning cyclists surveyed, 3 experts interviewed, and failing any one meant changing the positioning, not the evidence.
Transport multiple bicycles securely and efficiently with an electric vehicle in the United Kingdom.
01Define
Unsure an EV can carry more than 2 bikes, or what the weight does to range.
02Locate
Few racks made for EVs, unclear fit, and reviews scattered everywhere.
03PrepareInstallation
Complex fitting, tools, and the risk of marking the car.
04ConfirmSecurity
Heavy e-bikes are hard to secure, and nothing shows they are.
05ExecuteRange
Range drops, drag rises, and the car handles differently.
06MonitorSecurity
Stopping to check the bikes, and worrying about theft.
07Modify
Adjusting on the road without the tools or the know how.
08ConcludeInstallation
Scratched paint, and a rack that takes long to come off.
Mapped before the survey went out. The marked stages are where the survey and interviews found the same pain. Looks and warranty matched 2 emotional jobs: take pride in how it fits the EV, and protect the car's long term value.
- Range preservationHigh17 of 23
- Installation effortHigh14 of 23
- Warranty concernsLow13 of 23
- Security, anti theftMedium11 of 23
- Aesthetic integrationMedium11 of 23
- Installation accessMedium10 of 23
- Price resistanceMedium to low8 of 23
01 · Survey and interviews
3 outcomes reach top quartile importance
Range, installation and security did
02 · Survey, cross checked against Bike Europe
Modal willingness to pay matches the £1,500 to £1,800 band
It did, and matches premium rack pricing
03 · Survey, same respondents
Adoption intent improves by 10% to 15% once the aero case is shown
6 people moved from maybe to yes, a 15% lift
04 · Automotive, investment and retail interviews
Experts confirm an OEM or direct to consumer route is feasible
Both confirmed, with conditions
Automotive design
Rear hardpoint integration is technically possible.
Adoption depends on documented compliance for lighting, plate visibility and load limits, plus empirical aero and structural data. Test results, not opinions.
Mobility investment
The category is fundable.
Show acquisition, pre orders and unit economics before going near an OEM. Use financing to take the price barrier down early.
Cycling retail
Families and e-bike owners will want this.
Centralised installation is the operational problem. Build a regional installer network, and get into the tax advantaged cycling schemes.
The unexpected finding was warranty. 12 of 20 named it, and it is not about the rack: they fear that bolting anything to a new EV voids the cover on the car. That made compliance part of the product, which is why the pricing below sells it rather than footnotes it.
Sell it as a system, not as a rack
03Positioning, price
Sold as a rack, it fights Thule on price and compatibility, which a patent does not win. So the value curve gets rebuilt: drop what costs range, raise what only an EV owner values, and price against the delta rather than the shelf.
Eliminate and reduce
- Drag that costs range
- Cumbersome installation
- Afterthought aesthetics
- Ambiguous compliance
Raise and create
- Wake aware aerodynamics
- Install once, deploy on demand
- EV aligned design
- Compliance documentation
- E-bike readiness
- White glove service
Compete on what the category already competes on and the patent is worth nothing. These ten decisions are what makes it a different product rather than a better rack.
- Range preservation25%3 to 8
- Ease of installation20%4 to 8
- Security18%6 to 7
- Aesthetic integration14%5 to 8
- Compliance and warranty13%5 to 8
- Service access10%7 to 8
5.2 to 8.2
+3.0 weighted
And the uplift sits on range and installation, which is what the survey said it cared about. That is the whole argument for the price below.
Priced against the value, fenced by tier
Core
£1,495
The validated pain points, and nothing else
- Integrated chassis
- Deployable carrier, 2 bikes
- Lighting and plate visibility
- Baseline lock
Performance
£1,795
Families and club riders carrying heavier, higher value bikes
- Everything in Core
- Reinforced e-bike load modules
- Quick assist loading arms
- Premium trims
Security+
+£149
Buyers whose bikes are worth more than the rack
- Upgraded locks
- Anchor mounts
- Tracker recess
Value based, not cost plus: priced off the PUV delta and the survey's willingness to pay, fenced so you only pay more where you get more. Instalments over 12 to 24 months take the upfront barrier down.
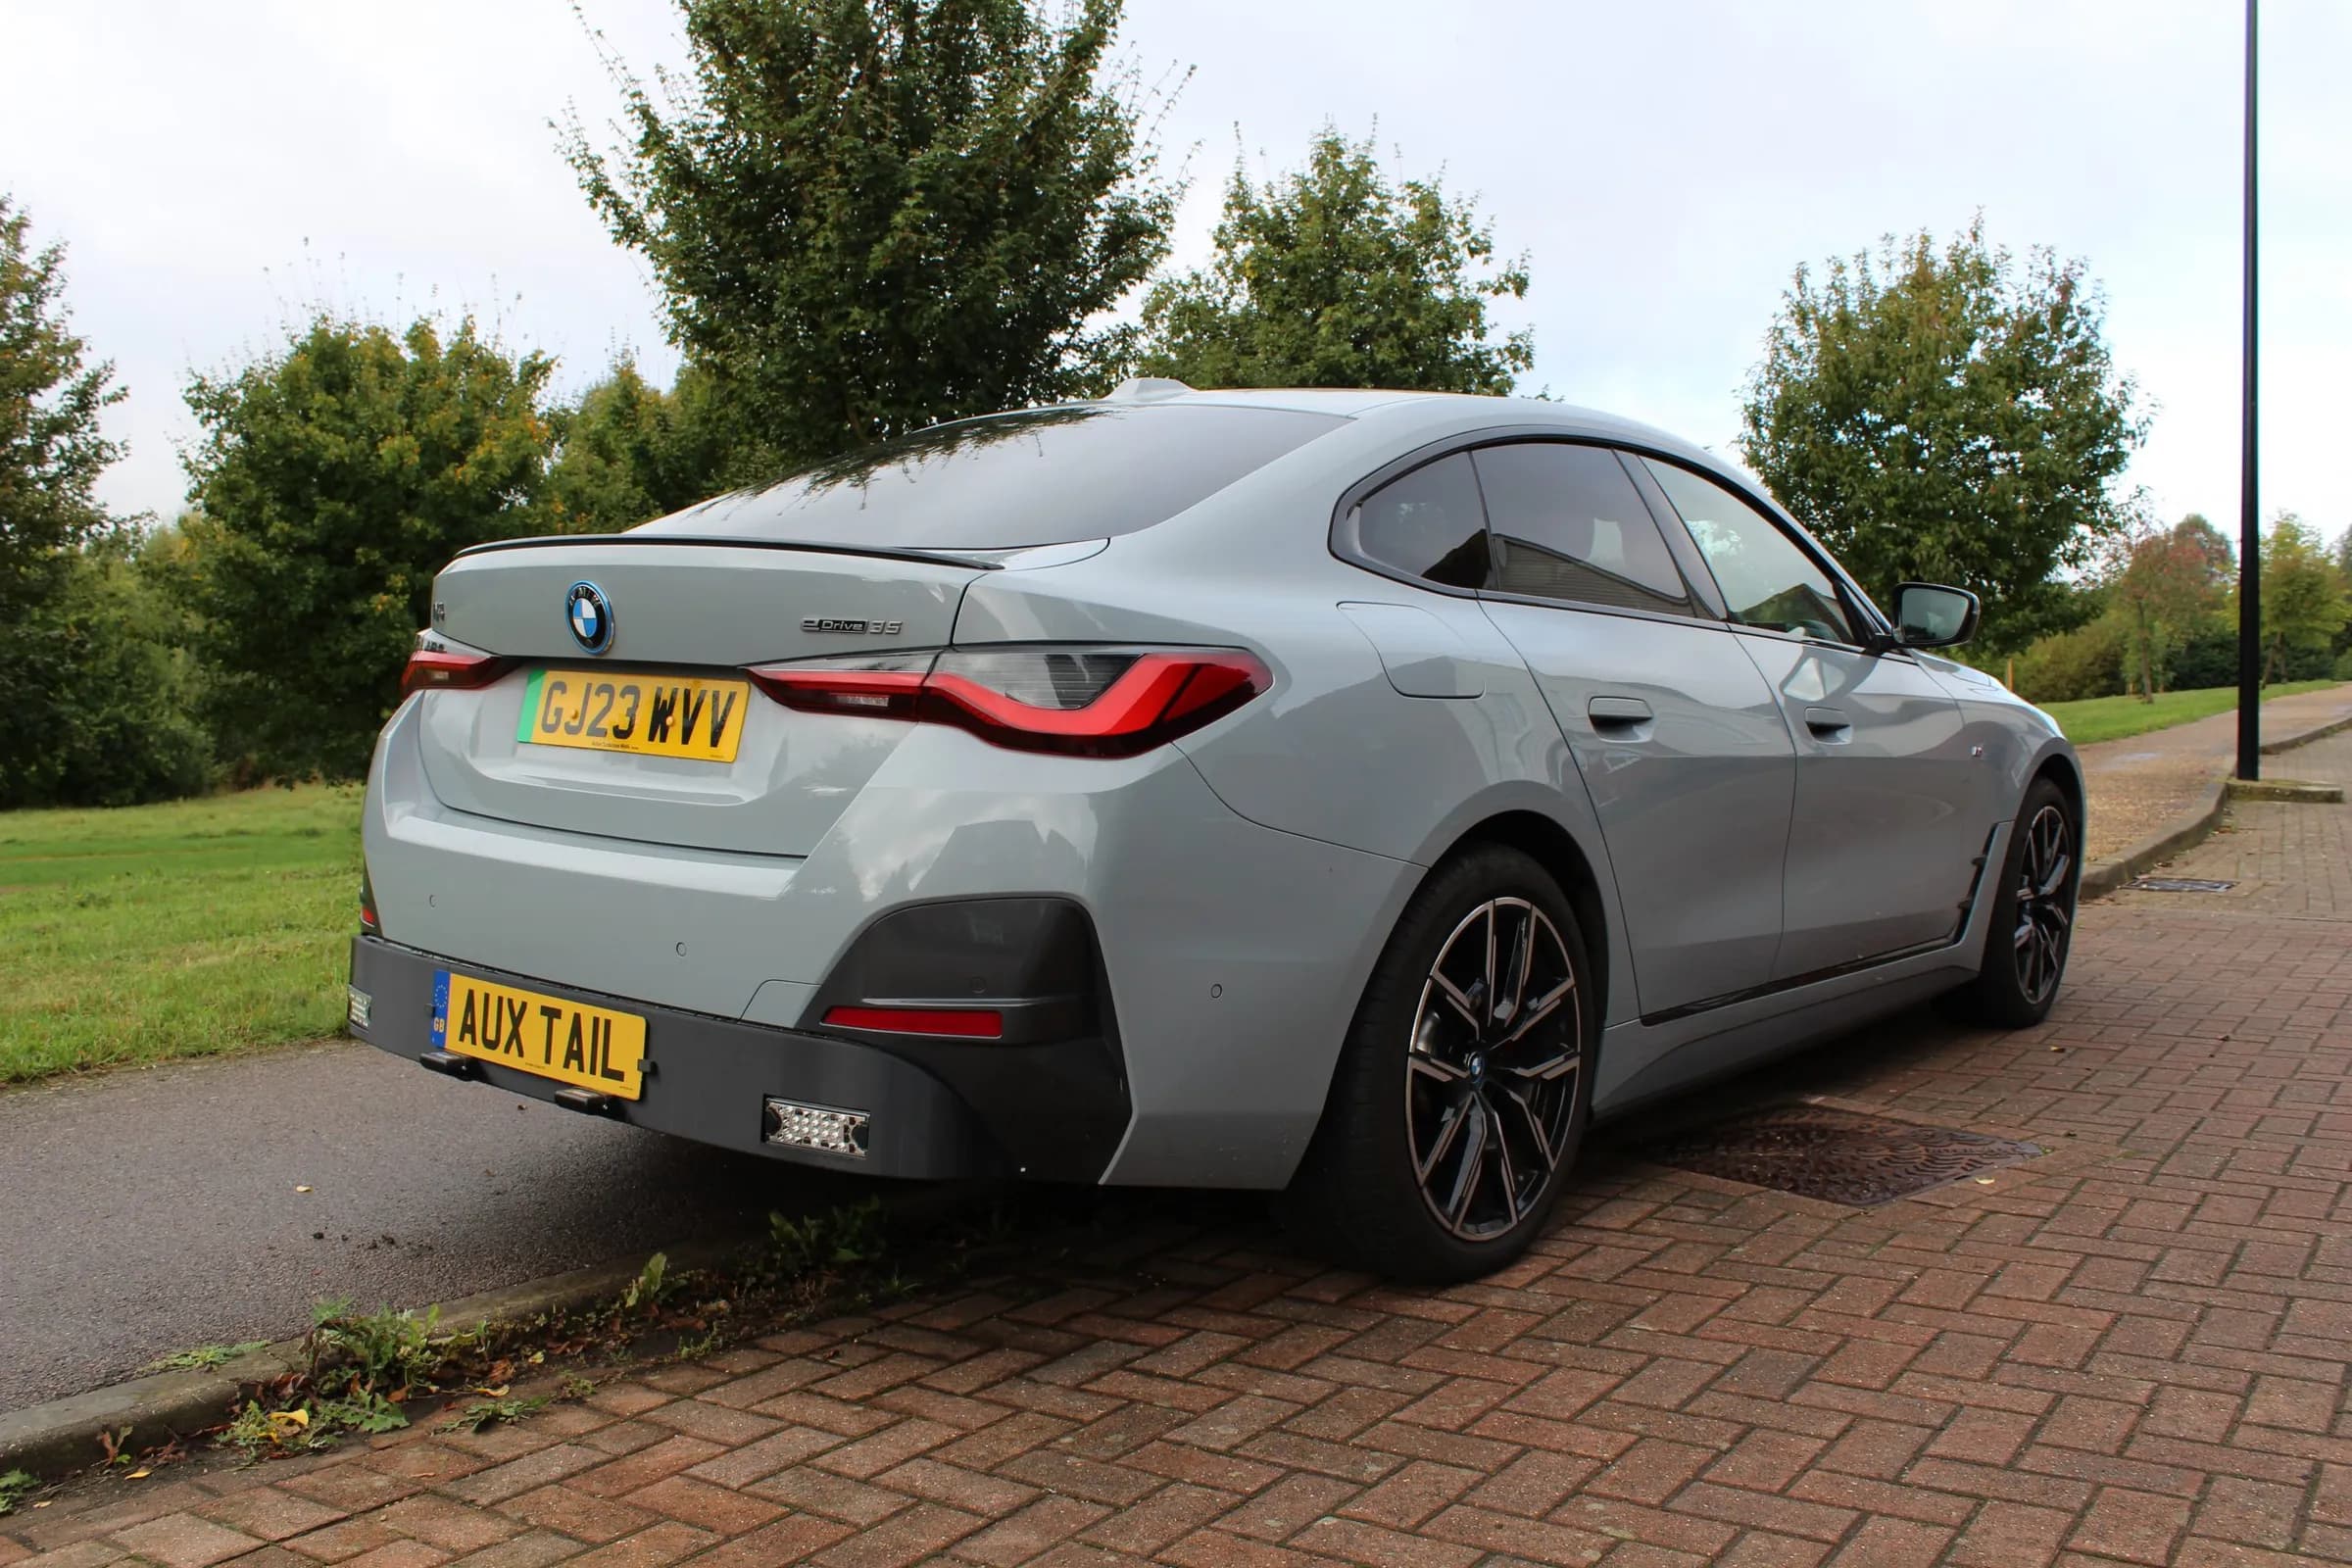
Four ways in, one to start with
Auxtail
Retail first
No
Halfords brings reach and takes the margin with it, and a shop floor cannot sell a drag coefficient. The product gets commoditised next to the racks it is beating.
Fleet and institutional
Later
Councils and clubs buy in volume, slowly, on price. Wrong first customer for a premium product with no track record.
OEM licensing first
Not yet
Legitimacy and dealer networks, in exchange for years of approval cycles and testing spend before a single sale. Entering here without consumer proof can stall the venture.
D2C with certified installers
Start here
Keeps the narrative, the margin and the feedback loop, and a certified installer answers the warranty fear directly. It is also the only route that produces the evidence an OEM will later ask for.
The timeline, with the gate on each
- Phase 00 to 3 months
Seed proof
10 to 25 units placed across regions, aero and installation data collected and published.
Gate
Returns at or under 5%, NPS of 55 or better - Phase 13 to 9 months
OEM licensing prep
1 hero EV model targeted, dealer pilots run, licensing and royalty terms negotiated.
Gate
Dealer install at or under 45 minutes, warranty events at or under 1% - Phase 29 to 18 months
Early majority bridge
2 to 3 more EV models fitted, installer network to 10 to 15 partners, Performance tier launched.
Gate
CAC payback within 6 months, installer NPS above 60
Key partners
- EV makers, for legitimacy and dealer networks
- Cycling retailers and installers, for reach
Key activities
- Design and manufacture to aero and compliance standards
- Direct marketing, clubs and event demos
Value propositions
- Range kept
- Easy to fit and remove
- Looks like part of the EV
- A system, not a bolt on
Customer relationships
- Fit check and a pre order waitlist
- Certified installers
- Clear warranty and aftercare
Customer segments
- Affluent EV owning families
- Cycling and triathlon clubs
- Later: OEMs, fleets and councils
Key resources
- The rear integration patent
- Aero and structural test results
- The founder's experience
Channels
- Online configurator and shop
- Roadshows with EV and cycling clubs
- Later: OEM dealers and retailers
Cost structure
- Manufacturing, the largest
- Marketing and sales
- R&D for new EV models
Revenue streams
- Core £1,495 and Performance £1,795
- Security+ and add ons
- Installation by certified partners
- Later: OEM licensing royalties
Warranty
A failure or a compliance gap undoes trust, and the OEM talks with it.
Compliance certification packs, and OEMs brought in early.
Aero varies by car
The drag saving may differ from 1 EV shape to the next.
Test across models, and publish ranges rather than 1 number.
Uneven installers
A poor fitting hurts both satisfaction and safety.
Certification, standard procedures and ongoing checks.
Price resistance
A premium price meets resistance, even in premium segments.
Financing, bundles, and showing the value plainly.
Supply delays
Manufacturing ventures run late.
Dual sourcing, and small pilot batches.
4 numbers to watch
- Acquisition
- New customers per period, by campaign, event and installer referral.
- Satisfaction
- NPS, warranty feedback and post install surveys.
- Engagement
- Use of the configurator, the forums and social media.
- Conversion
- Prospects who go from awareness to a deposit or a purchase.
Underneath all of it is one sequence: prove it with your own customers, then sell that proof to the people who can scale it. D2C is not the destination. It is how you earn the meeting.
4 key decisions
04What it cost
Every section above says what I recommended and why. None of them says what it costs to be right, so this one does.
What is actually being sold
Not taken
A better rack
Shipped
A system, sold on the delta
How I got there
Sold as a rack it fights Thule on price and compatibility, and a patent does not win that fight. So the value curve gets rebuilt instead of the product being re-specified.
What it cost
- Buyer
- You buy compliance and a fitting, not a box off a shelf.
- Operations
- 6 things to raise or create against 4 to drop, and the 6 are the hard ones.
- Business
- Every unit now carries a service promise, not just a shipment.
Where the price comes from
Not taken
Cost plus, against the shelf
Shipped
£1,495, off the value delta
How I got there
The perceived use value moved 5.2 to 8.2, and the survey's own willingness to pay landed inside £1,500 to £1,800. The price is argued from those 2 numbers rather than from what the shelf charges.
What it cost
- Buyer
- 2x to 2.5x the premium rack sitting next to it.
- Operations
- Every sale needs the aero and compliance case made, not just stocked.
- Business
- Small volumes. The launch target is 2,603 people, not a category.
Which door to knock on first
Not taken
OEM licensing first
Shipped
Direct, with certified installers
How I got there
OEM first buys legitimacy and a dealer network in exchange for years of approval cycles before a single sale. Entering there without consumer proof can stall the venture.
What it cost
- Buyer
- An installer visit, not a box that arrives.
- Operations
- A regional installer network to build, from 0 to 15 partners.
- Business
- 18 months of proving it yourself before the OEM conversation.
What to do with the warranty fear
Not taken
A line in the manual
Shipped
A compliance pack you are sold
How I got there
12 of 20 named warranty, and it is not about the rack: they fear that bolting anything to a new EV voids the cover on the car. A footnote does not answer that.
What it cost
- Buyer
- The thing that removes the fear is also the thing costing you money.
- Operations
- Lighting, plate visibility, load and aero, tested and documented before launch.
- Business
- Per model work: 1 hero EV first, then 2 to 3 more behind it.
Auxtail Pitch Deck
058 slides
Everything above, compressed into the artefact it was for: the problem in numbers, the market in 3 tiers, the product, the business model, the ask, and the way out.
Step through with the arrows, the dots, or the left and right keys.
Pitch deck · 01 Title
What a designer learns doing this
06Reflection, next
I came in as an industrial designer and spent it on what design school leaves out: what it costs, who pays, why anybody says yes. The journal opens on mechanisms and closes on pricing fences, which is the distance travelled.
Evidence beats conviction
4 thresholds went down in writing before the survey went out, so the findings could have killed the positioning. That is the only reason meeting them counts.
The objection is rarely the product
Nobody doubted the rack. They doubted their warranty, their range and the install, and the strategy answers those 3 while the hardware barely changed.
Outside forces shape the product
Regulation caps the load at 70kg, OEM approval sets the clock, retail takes the margin. 3 parties shaped this product before a customer ever saw it.
Pricing is a design decision
A tier is a fence: what sits inside it, and what a buyer has to want badly enough to cross it. That is drawing, not accounting.
A patent is not a business
The engineering was finished and protected before I arrived. Everything between that and somebody paying for it was still missing, and it was the harder half.
The whole cycle, end to end
Costs, margins, channels and gates, and how they move each other. Knowing that is what lets me sit between engineering, finance and sales and use each one's words.
Next is Phase 0: 10 to 25 units in real driveways, the aero and install data published, and that evidence taken to pre seed funds and mobility accelerators. Everything above is a plan until somebody's bikes are on the back of their own car.
The project
Deepakkrishna Ramachandran
Project owner, commercial strategy
Ali Junaid Ahmad
Project mentor, course leader MSc IAE, WMG
Craig Broadbent
Auxtail founder, ex-design engineer at Nissan